Showing posts with label Lawsuit. Show all posts

Tuesday, September 30, 2014

Los Angeles County Superior Court Accuses Prominent Foreclosure Attorneys Philip Kramer and Mitchell Stein and at least 17 other individuals and businesses of ensnaring Borrowers in a Scheme that Falsely Promised a Cut of Future Settlements

APNewsBreak: Lawyers accused of scam in bank suits
California prosecutors sued several lawyers and call center operators for allegedly duping desperate homeowners across the country into paying thousands of dollars to join dubious lawsuits against big banks.
Top comments Hide / Show comments
No comments have been posted to this article.
Start the conversation >
COSTA MESA, Calif. —
California prosecutors sued several lawyers and call center operators for allegedly duping desperate homeowners across the country into paying thousands of dollars to join dubious lawsuits against big banks.
The complaint unsealed Thursday in Los Angeles County Superior Court accuses prominent foreclosure attorneys Philip Kramer and Mitchell Stein and at least 17 other individuals and businesses of ensnaring borrowers in a scheme that falsely promised a cut of future settlements.
The lawsuit portrays the defendants as the most recent in the chain of mortgage-related scammers who helped fuel the housing bubble and have cashed in on its collapse. The defendants previously worked in the fraud-ridden loan modification industry, in which lawyers offer to negotiate better mortgage terms on behalf of troubled borrowers in exchange for a fee.
They are accused of telling borrowers that they had a solid claim to being victims of predatory lending because courts had already found most lenders to have approved inappropriate mortgages.
"They essentially took advantage of what we know is a growing sentiment out there," California Attorney General Kamala Harris said Thursday. "They suggested that by joining this lawsuit, the banks would have to pay. But the only people who paid were those homeowners who were victimized for the second time."
Investigators are aware of some 2,500 California residents who have been listed as defendants in the lawsuits, but there could be many more who paid fees and were never actually added to the suits or are out of the state, Harris said.
Up to 2 million official-looking mailers advertising the lawsuits were sent to homes in at least 16 other states, including Arizona, Florida, Nevada, New York and New Jersey, Harris' office said in a release.
Some borrowers had their homes foreclosed on after paying to join the suits filed by Kramer and Stein, according to the complaint.
Defendants in the complaint are all based in California, but the investigation could eventually ensnare associates in other parts of the country.
Florida bar spokeswoman Zannah Lyle confirmed that her organization was looking into allegations of rule violations concerning Tallahassee-based lawyer and lobbyist David Ramba's work with Kramer to recruit struggling homeowners to join lawsuits against banks. Ramba did not immediately respond to a message seeking comment.
The attorney general's complaint was unsealed a day after state bar investigators and state Department of Justice agents served defendants with copies of the complaint at 14 locations in Los Angeles and Orange counties.
Officials loaded boxes of seized documents into moving vans Wednesday. Armed police guarded the entrances to emptied offices, which appeared to contain wall-to-wall cubicles for phone center workers. The Orange County raids took place in sprawling office parks with manicured lawns surrounding Irvine's airport.
Outside one office, a man in a business suit said he had worked for the raided company but refused to answer any other questions as he carried a stack of framed pictures from the building and oversaw the removal of a small refrigerator by younger apparent employees.
At another office, a manager who would only give his first name, David, said he and his colleagues had been questioned about their connection with Kramer. He said they had done business with the lawyer two years ago but not since.
Prosecutors accuse the defendants of making false representations and three counts of unfair competition. They are seeking an injunction stopping the defendants from continuing with the business in addition to unspecified monetary damages.
No criminal charges have been filed in connection with the case.
Kramer's firm and the other defendants' were placed into receivership on Monday and have had their assets seized, the attorney general's office said.
Harris said that bar association lawyers were reviewing the suits against the banks to determine whether any plaintiffs had legitimate complaints that could be pursued against the lenders.
Calls to Kramer's office were being forwarded to a state bar phone number Thursday. Calls to Stein, who refers to himself on his firm's website and other communications as "The Doberman," went straight to a busy signal.
Prosecutors accuse Kramer and Stein of exploiting an existing lawsuit known as Ronald v. Bank of America NA filed in Los Angeles Superior Court in March 2009. Stein was one of the lawyers who first filed that case, which alleged on behalf of a few dozen clients that the bank committed mortgage-related improprieties. Kramer later joined as counsel to another defendant who was added to the case.
The lawyers used the Ronald case to drum up business and have since filed separate lawsuits against JPMorgan Chase & Co, Wells Fargo Bank NA, Citibank NA and others to broaden their base of clients, the complaint alleges.
The lawyers and their associates sent mailers that looked like official class-action lawsuit notifications and stated that their recipients were potential plaintiffs in a litigation settlement. The letters claimed they could cut their mortgage to as little as 70 percent of their value, prevent foreclosure and get $75,000 in damages.
They directed people to phone supposed law offices that were actually call centers staffed by operators with no legal expertise.
In addition to using mailers, Stein used his law firm's Facebook page to make overblown claims about bank behavior and his ability to seek retribution, according to the complaint.
"Look for Patriot Act violations in your mortgage," Stein wrote in a Jan. 17 posting. "Talk to a lawyer. You might just cancel the mortgage."
Prosecutors estimated hundreds or even thousands of people paid between $5,000 and $10,000 to join the lawyers' suits.
Kramer gloated in an October 2010 e-mail to another defendant about the virtues of their new undertaking compared with the loan modification business.
"Only morons would prefer to `sell' mods from this day forward," Kramer wrote, according the complaint.
Bank records show more than $7 million deposited in three of Kramer's accounts connected to the investigation, with millions more paid to call centers that provided answers to prospective clients responding to the mailers, the complaint said.
Those workers are accused in the complaint of overstating lawyers' progress in the lawsuits, all of which are in their earliest stages, and of misrepresenting judges' apparent disposition toward the banks.
Some salespeople are alleged to have told borrowers that the judge in the Ronald v. Bank of America has told the lender it has "no defense" and that its main argument is "absurd."
The salespeople also tell homeowners that the case's lawyers have proven banks have taken money from investors that can't be accounted for, the complaint says.
Philip Warmanen, a 71-year-old travel agent in Jacksonville, Fla., was among those who joined the lawsuit. Warmanen said he responded to a mailer that turned out to be from Kramer's law firm early this year after Bank of America failed to offer him a modification on his home that had lost about half its value since he paid $525,000 for it in 2006.
Warmanen was told he should receive a modification and other settlement benefits in just a couple months when he paid $4,000 to join the lawsuit but has heard little of the case since then.
"They said there was a strong likelihood that this would be successful and that they had a few cases where the judgment had come through positively in favor of the complainants," he said. "They led me to believe that that might be my case."
---
Jacob Adelman can be reached at http://twitter.com/jacobadelman

Thursday, August 2, 2012

Los Angeles Sues U.S. Bank, Calls It a 'Slumlord'

 
By Jonathan Stempel

The city of Los Angeles has sued U.S. Bank, accusing a unit of the fifth-largest U.S. commercial bank of becoming one of its biggest slumlords and blighting the city by allowing hundreds of foreclosed homes to fall into disrepair.

Monday's civil lawsuit by the office of Los Angeles City Attorney Carmen Trutanich alleges that U.S. Bank has taken title to more than 1,500 foreclosed residential properties in the city in its role as trustee for various mortgage-backed securities trusts.

Los Angeles said that at least since July 2008, U.S. Bank has "disregarded virtually every one of its legal duties and responsibilities as owner, resulting in the creation and maintenance of an alarming number of vacant nuisance properties and substandard occupied housing units."

It said the bank has ignored repeated demands that it comply with the law, causing hundreds of homes to become uninhabitable or "public nuisances," and resulting in illegal evictions of hundreds of tenants from the second most-populous U.S. city.

Los Angeles said that it is seeking a civil fine of $2,500 a day for each violation by what it called "one of the largest slumlords in the city." It estimated the bank's potential liability to be in the "hundreds of millions of dollars."

Thomas Joyce, a spokesman for Minneapolis-based U.S. Bank, said it is the mortgage servicers, not the trustee, who have the responsibility to maintain foreclosed properties, and that "we intend to bring them into" the lawsuit.

Joyce also said the city only recently agreed to detail which homes needed better upkeep, and that the bank will "stand ready" to address property-specific and general foreclosure concerns as it has done in other cities.

Other Cities' Lawsuits

Other large U.S. cities have also sued over mortgage industry practices that they allege contributed to urban blight.

Wells Fargo & Co, the nation's largest mortgage lender, in May settled a lawsuit by Memphis, Tenn., and on July 12 it settled a similar case involving Baltimore.

The Baltimore accord was reached in connection with the San Francisco-based bank's $175 million settlement with the federal government over allegations that it overcharged black and Hispanic borrowers on mortgages, contributing to higher foreclosures.

Wells Fargo was one of five big servicers to join February's $25 billion U.S. settlement over foreclosure abuses.

The National Fair Housing Alliance filed discrimination complaints with the federal government in April against both U.S. Bank and Wells Fargo, accusing them of doing a better job maintaining foreclosed homes in white neighborhoods than in minority neighborhoods.

According to the 2010 census, Los Angeles had 1.41 million housing units, of which about 95,000 were vacant. The city's population was about 3.79 million.

Shares of U.S. Bancorp were down 9 cents at $32.69 in morning trading on the New York Stock Exchange.

The case is People v. U.S. Bank NA et al, Superior Court of California, Los Angeles County, No. BC488436.

Copyright 2012 Thomson Reuters. Click for restrictions.
Enhanced by Zemanta

Friday, October 28, 2011

WHAT ABOUT HOMEOWNER HOSKING? WAKE UP AG KAMALA HARRIS AND DOBERMAN MITCHELL J. STEIN AND HELP VIRGINIA HOSKING WHO IS SCARED OUT OF HER MIND, WAITING TO BE FORCED FROM HER HOME. FOCUS!


Lawyer accused of mortgage-related fraud sues attorney general

Jeff Turner/Flickr
Los Angeles-area attorney Mitchell J. Stein refers to himself as "The Doberman" and his website advertises, "You Hold The Leash."
In August, California Attorney General Kamala Harris raided Stein's offices and accused him and other lawyers of fraudulently misleading thousands of struggling homeowners into paying to be part of mass lawsuits against mortgage lenders like Bank of America.
But Stein sued back, after warning on his Twitteraccount that "The Doberman is about to take a large bite out of Kamala Harris." Stein has accused the attorney general of being "the pawn of America’s most powerful banks,” claiming that Bank of America "corruptly funneled money" to Harris, according to one of his lawsuits.
As the legal sparring continues, the alleged fraud victims are running out of time.
Virginia Hosking received a notice last week directing her to vacate her foreclosed Whittier house within three days.
Report an error: See something wrong in this story?
E-mail our editors.
"Now I’m sitting here freaking out, afraid to walk out my front door in case they come lock me out," Hosking said.
Hosking said her husband had just passed away and she was facing foreclosure last year when she paid $4,000 to another law firm targeted in Harris' fraud suit.
Hosking said she was told that joining the lawsuit against her mortgage lender, Bank of America, would help save her house. At some point, Stein's firm, which has been suing Bank of America since 2009, took charge of Hosking's case.
The attorney general accused the lawyers of deceiving homeowners into thinking that the lawsuits would stop foreclosures or reduce their mortgage payments. In a press conference announcing the action, Harris called it "work that will bring justice to many homeowners in California who were targeted by predators who happened to have a law license."
Stein, who signs e-mails with a picture of a Doberman pinscher, claims that he is "Bank of America’s biggest nightmare" and that Harris' suit puts struggling homeowners at risk.
He points out that Harris received four donations in February, totaling $1,500, from attorneys with the law firm representing Bank of America.
Stein's recent lawsuit accuses Harris of doing the bidding of Bank of America by removing "the superstar who had been beating the bank to a pulp for two and a half years."
Shum Preston, a spokesman for Harris, called the suit frivolous.
"We respectfully decline to address the very strange claims made in this lawsuit," he said in a statement. "It is, sadly, another example of what we uncovered during our investigations: false promises designed to lure already distressed homeowners into paying money to lawyers who refuse to properly represent them."
A Bank of America spokeswoman declined to comment.
Stein's office sent e-mails to clients like Hosking asking them to show up at a court hearing to support Stein "in the fight against bank and government corruption."
His firm sent out a press release that said hundreds of homeowners would gather in solidarity with the Occupy Wall Street movement and "against Ms. Harris' support of the 1%."
Meanwhile, the State Bar of California obtained a court order stating that Stein "has become incapable of devoting the time and attention to ... his law practice" and authorizing the bar to seize his files and freeze his bank accounts.
Stein, however, maintains the order doesn't apply because it names Mitchell J. Stein and Associates and not his newer partnership, Mitchell J. Stein & Associates LLP. For the same reason, Stein's website states, "this law Firm has never been sued by the State of California."
Stein is also trying to stop seizure of his assets through his Florida bankruptcy proceeding.
The state bar notified Hosking that she could pick up the confiscated files relating to her, but she would have to find another lawyer.
Hosking keeps getting solicitations promising to save her house if she pays a fee.
"There are all kinds of preying people out there. I don’t know who to trust anymore," she said.
The state bar will work to return money to alleged victims from Stein's frozen funds, said Suzan Anderson, an attorney for the bar. Authorities also are encouraging banks to give a break to people like Hosking.
"Right now, the attorney general and the state bar are discussing with the lenders how they might be able to put a hold on any foreclosures because of these actions and maybe work with the people and give them time," Anderson said.


Enhanced by Zemanta

Friday, August 26, 2011

BOMBSHELL AT LIVING LIES


Bombshell Admission of Failed Securitization Process in American Home Mortgage Servicing/LPS Lawsuit

MOST POPULAR ARTICLES

EDITOR’S NOTE: It is comforting to know that at least some people are paying attention. From one of the largest servicers in the country comes an admission that securitization of mortgage loans was an illusion. The facts alleged by AHMSI  in its lawsuit against LPS are true in virtually all cases in which any bank or other entity has claimed an interest in a mortgage loan.
They are actually saying two things: first, they are saying that their practice was to create the documents supporting the foreclosure by an entity that was essentially picked at random and that these documents were created only as necessary in foreclosure litigation (otherwise they just proceeded with any old documents); second, they are saying that the people who signed those documents lacked any authority or appointment to represent any real party in interest and that the signature was forged on behalf of other people who also lacked any authority or appointment to represent any real party in interest.
In the four years that I have been analyzing and writing about this mortgage crisis it has been my consistent opinion that the original mortgage transaction was a single transaction between a borrower and the lender. The single transaction doctrine or the step transaction doctrine utilized in a myriad of other cases involving both real property law and commercial transactions create simplicity out of what appears to be a complex series of transactions. I have repeatedly said in my writings and in my presentations at seminars that those who participated in the securitization scam would prevail as long as they were able to direct the attention of a judge to only one part of the transaction, to wit: the part where the borrower receives the benefit of funding a loan. The burden is on borrowers to redirect the attention of the judge to include both sides of the transaction.
The lender’s side of the transaction is as simple as the borrower’s side. The lender funded or advanced money for the purpose of funding a mortgage loan. The pretender lenders don’t want any judge looking behind the veil. But the facts are clear. The lender in the transaction was a group of investors who never received any notice of the transaction with the borrower, much less the actual note and mortgage. The investor/lender received a mortgage bond that was supposedly backed by a perfected mortgage lien on the property owned by the borrower. Instead of naming the lender as the mortgagee, nominees were inserted into the documents executed by the borrower. The failure to disclose both the identity of the lender and the terms under which the lender advanced money (contained in the prospectus and the pooling and servicing agreement) results in an imperfect lien. (The test for a perfected lien is being able to determine the identity of the party from whom you would obtain a release).
At the time of the original transaction the party designated as the “lender” was powerless to execute a satisfaction of mortgage. By definition this means that the lien was never perfected. With few exceptions all of the entities that have been involved in the initiation of foreclosure proceedings have been nothing more than middlemen pretending to represent the investor/lender when in fact their intent was to divert money, proceeds, and property from the investor/lender into their own pockets. In order to do this the pretender lenders must actually foreclose on property and conduct what purports to be a foreclosure sale and continue billing fees against the revenue stream that is due to the investor/lender. When they get to zero balance because the property value is lower than the amount due to the servicer or other middleman, the property goes to the middleman instead of the investor/lender.
This is why there can be no widespread modifications, short sales, or any mediated settlement in which the immediate result is either reinstatement of the mortgage or cash proceeds–both of which would have to be reported and paid to the investor/lenders. Nobody on Wall Street wants the investors to get anything and the borrowers are viewed with complete disdain. Who cares about them?
If the original transaction is simply viewed for what it is–a transaction between the borrower and the investor/lender the solution to the mortgage mess becomes clear. The only actual function of the intermediaries in the securitization process is to act as conduits for clearing transactions. It is obvious that they have intentionally failed to act in accordance with the requirements of the pooling and servicing agreements and the prospectus that was given to the investor/lenders. If they were playing fair they would have disclosed the identity of the actual lender and the terms of payment to the actual investor/lender. That would include payments received from the borrower as well as numerous third parties based upon factors that were not necessarily related to payments by the borrower. The transaction in which the investor/lender advanced money was based upon liability and guarantees from multiple parties.
The facts here are actually quite simple. The wrong party was designated on the note and the mortgage. Vital terms of repayment or omitted from both the note and the other disclosure documents in violation of the requirements of the federal truth in lending act. The intermediaries were only interested in the money trail and they knew they would create whatever document trail was necessary to support what they had done with the money. This is like your bank failing to post a deposit transaction or making claims on a transaction between you and a third-party in which a payment by check was involved. The bank is merely a conduit and has no rights in the principal contract between you and that third-party. This is established law. Yet in the mortgage mess the banks have succeeded in convincing judges that their mere presence as intermediaries is sufficient to establish themselves as agents for everyone. This success has not been without substantial rewards. It is the intermediaries who are taking the houses and eventually the proceeds at a cost to and detriment of the investor/lenders and the borrowers.
The borrowers have no way of knowing the actual balance due on their obligation since the intermediaries refused to provide any accounting for the receipt of any funds from any party other than the borrower. This keeps the judges attention focused on the borrower and whether the borrower made payments–instead of requiring proof that a payment was due, and if due, to whom? By requiring borrowers to deal with intermediaries instead of the principals the banks have succeeded in creating an impenetrable barrier to modification or settlement of these defective mortgage loans.
 The bottom line is that the securitization of mortgages loans never actually happened. The defects in the origination process, the absence of transfer documents and delivery in accordance with the pooling and servicing agreements are incurable. It is simply not possible to require an investor/lender to accept the transfer a loan, obligation, receivable, note or mortgage that is already in default and that had never been perfected as a lien. This leaves the record clouded with a “mortgagee” or “payee” to whom no money owed. While it is possible for the investor/lenders to assert claims and perhaps establish equitable or judgment liens, they have not shown any desire to do so. The record is devoid of any attempts in the last 10 years of any such attempt.
Thus the lien is (a) unenforceable by anyone and (b) being enforced by parties who wouldn’t have the right to try, but for the willingness of the Courts to look at only the whether the borrower made payments instead of requiring proof as to whether a payment is due, the actual balance and to whom it is owed.

BY YVES SMITH

Bombshell Admission of Failed Securitization Process in American Home Mortgage Servicing/LPS Lawsuit

Wow, Jones Day just created a huge mess for its client and banks generally if anyone is alert enough to act on it.
The lawsuit in question is American Home Mortgage Servicing Inc. v Lender Processing Services. It hasn’t gotten all that much attention (unless you are on the LPS deathwatch beat) because to most, it looks like yet another beauty contest between Cinderella’s two ugly sisters.
AHMSI is a servicer (the successor to Option One, and it may also still have some Ameriquest servicing). AHMSI is mad at LPS because LPS was supposed to prepare certain types of documentation AHMSI used in foreclosures. AHMSI authorized the use of certain designated staffers signing with the authority of AHSI (what we call robosinging, since the people signing these documents didn’t have personal knowledge, which is required if any of the documents were affidavits). But it did not authorize the use of surrogate signers, which were (I kid you not) people hired to forge the signatures of robosigners.
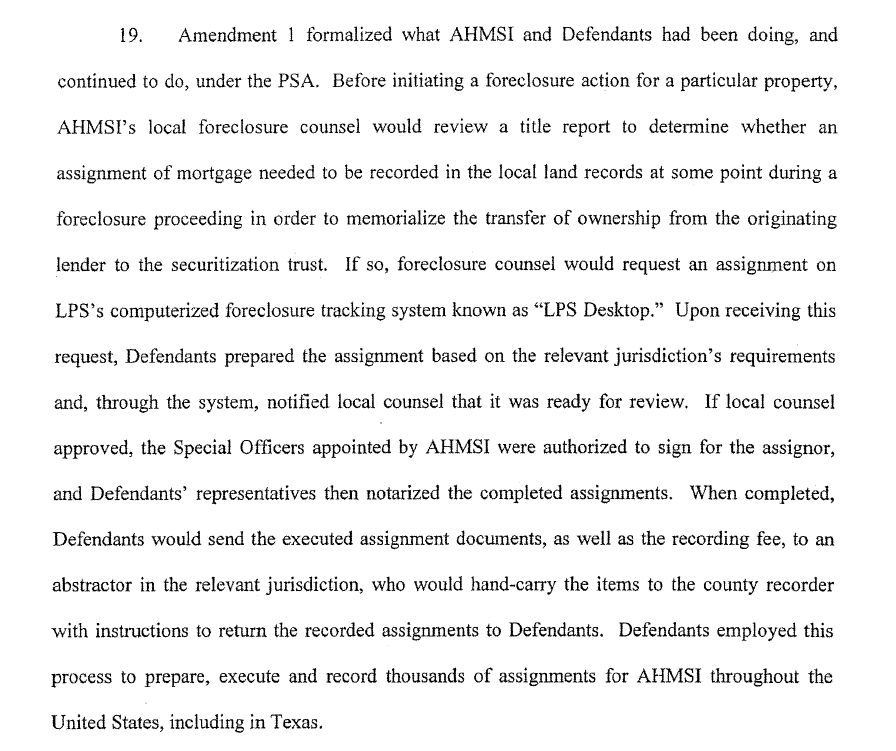
The lawsuit rather matter of factly makes a stunning admission (note that PSA here means Professional Services Agreement, and it was the contract between AHSI and LPS, click to enlarge):
Did you get it? They said that these procedures were standard between the two companies, which was to “..to memorialize the transfer of ownership lender to the securitization trust” right before initiating foreclosure. If you are a regular reader of this blog, you know that is impermissibly late. The note and mortgage had to get to the trust by a clearly specified date, usually 90 days after closing. As we’ve written numerous times, in the overwhelming majority of cases, the securitization entity was a New York trust, and New York trusts are like computer code, they can only operate exactly as stipulated. The exception was trusts by Chase and WaMu, which did allow for the originator to serve as custodian for the trust.
So AHMSI has just admitted that all of its foreclosures done with LPS were completed by the wrong party. In Alabama, wrongful foreclosures are subject to statutory damages of three times the value of the house, and recent cases have awarded much higher multiples of the property’s value. This little paragraph is a litigation goldmine for the right attorneys. I hope they have fun with it.
I’ve included the entire filing.

7 Responses

  1. In my situation the assignment of the mortgage (which occurred post BK discharge and right before foreclosure) was done in favor of a bank which has nothing to do with my loan. It is not the owner or investor trust per the MERS records. Why didn’t the servicer simply assign the mortgage to itself? I have reason to believe the assignee bank never even knew about the transaction or even that it is a plaintiff in this case. Anyone have thoughts or advice?

  2. @carie – where are you getting that position? i’ve seen you discuss it ad nauseum, but i admit i’ve never really following the reasoning

  3. More of the same BS:
    Neil said:
    “The bottom line is that the securitization of mortgages loans never actually happened. The defects in the origination process, the absence of transfer documents and delivery in accordance with the pooling and servicing agreements are incurable.”
    Neil—who are you protecting??? The securitization never happened, because the LOANS NEVER HAPPENED—
    THIS IS WHAT HAPPENED…and you know it:
    “…Subprime refinance was unsecured — a false and fraudulent mortgage — and nothing more than debt collection on a fraudulent transfer of collection rights to a false default debt. Everyone (in subprime refinance) was in (false) default before they even refinanced.
    The banks (as debt buyers) accomplished this by falsely placing borrower in current default (and never telling them) — and then the servicer purchases the collection rights from either Freddie or Fannie. Then the servicer “reinstates” the false default debt with a fraudulent refinance. And, if there is a subsequent refinance, that is just another transfer of collection rights. Servicer reports original F/F mortgage as “paid” — but it is “Paid-OUT” — by servicer purchase — and not “Paid-OFF” by the borrower as it should have been by the (fraudulent) subprime refinance. . Thus, borrower remains in default on F/F loan – despite a subprime refinance — and borrower can never refinance with an F/F again — They are doomed if they miss even one payment on the false collection rights — and will never recover because always held in default — on both the F/F loan and the collection rights. BUT BORROWERS should not be paying on fraud!!!! They have a right withhold payments on fraudulent debt.
    All fraudulent, all in violation of consumer protection laws — and, because the “creditor” of collection right never validates the “debt” — by disclosing the actual creditor to the false default debt — in violation of FDCPA and May 2009 TILA Amendment. Meaning borrowers should not be paying anything — because of fraud and violation of federal statutes.”

  4. @davies – indeed. no matter how evil you think the bank is, two wrongs don’t make a right as far as the courts are concerned. i’ve seem similar schemes result in a referral to the district atty from the judge

  5. Homeowners beware of filing any documents on the land title record that are bogus. It will eventually catch up with you and the law.
    Bank of America N. A. as successor in interest to Countrywide Bank N. A, and Bank of America Home Loan Services vs. Denise Honc, Dan Shabtai, Boyan Panajotov, Moonraven Medicine Bird, Does 1-100.

  6. Neil Garfield, you are an angel for pointing things out and pointing people in the right direction, Lawyers too. This is great news and I hope as you do too that lawyers get this and use this information to help homeowners who need this break! Thank you for being there.

  7. so many moving parts here, but how do you reconcile this with the premise that the security follows the note generally?


Enhanced by Zemanta